
Investing in a private real estate fund starts with understanding where your money goes, how it might earn returns, and when you can get it back. A property portfolio can look appealing while carrying risks that are easy to overlook.
Before signing anything, work through the offering documents and ask questions. You should be able to explain the investment in language, including what could go wrong.
Understand What the Fund Owns
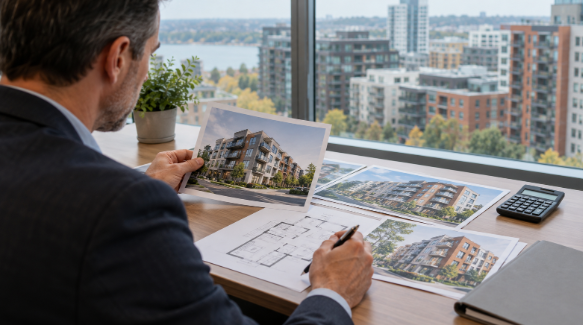
Start with the properties and the business plan. Does the fund own rented apartments, develop new buildings, lend against properties, or combine several approaches?
An occupied rental building has different risks from a construction project awaiting permits. Review locations, tenant demand, vacancy levels, and whether returns depend on rent, refinancing, or future sales.
Check the Manager’s Experience
Look for experience with the same property type and strategy. A strong history in apartment operations does not automatically demonstrate an ability to deliver development projects.
Ask for results from completed investments, including difficult periods. Check whether reported returns include fees and whether they reflect actual sales or estimates of what unsold properties are worth.
Review Fees and Conflicts
Management charges are only part of the picture. Depending on the structure, investors may also bear acquisition, financing, property management, and performance fees.
Request an example showing how earnings are divided between investors and the manager. Ask whether related companies provide services, how their prices are determined, and who reviews those arrangements.
Read the Withdrawal Rules
Private investments can be difficult to sell, and a stated redemption schedule does not necessarily guarantee immediate access to cash. Review the terms rather than relying on a sales presentation.
Questions worth asking include:
- Is there a holding period?
- How much notice must investors give?
- Can withdrawals be limited, delayed, or suspended?
- Could payments involve securities instead of cash?
Keep these restrictions in mind when deciding how much money you can commit.
Examine Debt and Distributions
Borrowing can increase gains, but it also increases pressure when income falls or financing becomes expensive. Ask how much debt the properties carry, when loans mature, and whether interest rates are fixed or variable.
Also check where distributions come from. Payments may include rental earnings, sale proceeds, borrowing, or returned capital. A regular payment does not, by itself, show that the fund is profitable.
Confirm Eligibility and Reporting
Some offerings are available to accredited investors in Canada under specific securities exemptions. Ask which exemption applies and what documentation supports your eligibility; qualifying does not establish that an investment suits your needs.
Request financial statements, reporting samples, and an explanation of how properties are valued. Find out whether statements are audited and how frequently appraisals occur.
Match the Commitment to Your Finances
Consider your emergency savings, existing property exposure, and upcoming expenses before choosing an amount. Several buildings in one region may still leave you exposed to the same local downturn.
Have an independent adviser review unclear terms and explain potential tax consequences. Resolve unanswered questions before transferring money, especially when the investment requires a long commitment.

